Coach Insurance Comparison
APC vs. Alternative Balance:
Coach Liability Insurance Comparison
Association of Professional Coaches (APC) and Alternative Balance both offer liability insurance for coaching, wellness, energy, and holistic practices, but the programs differ in Professional Liability structure, defense costs, Additional Insureds, included protections, service scope, optional coverage, and pricing.
APC vs. Alternative Balance: The Quick Answer
APC and Alternative Balance insurance programs are close in base annual price and top-line liability limits, but they differ in Professional Liability policy form, defense costs, additional insured fees, rented-premises coverage, and the pricing of certain expanded services.
Similar Top-Line Limits
Both APC and Alternative Balance offer $2 million / $4 million Professional Liability limits and $2 million / $4 million General Liability limits in the options reviewed.
Different Policy Forms
APC Professional Liability is occurrence-based, while Alternative Balance Professional Liability is claims-made. Both APC and Alternative Balance use occurrence-based General Liability coverage.
Defense Costs Work Differently
APC defense costs are outside the liability limits. Alternative Balance defense costs are within the Professional Liability limits.
Only $6 Apart in Base Price
APC Professional coverage is $275 per year. Alternative Balance Professional Membership is $269 per year, but some services and features may carry additional charges.
The takeaway: Price alone does not separate these two options very much. The bigger questions are how Professional Liability responds, how defense expenses affect your limits, what is included with the policy, and what may cost extra.
>
APC vs. Alternative Balance
Compare the policy features that may matter most when choosing liability insurance for your coaching practice.
A closer look at Client Accident Protection: Both programs include $25K in accidental medical benefits, but the remaining terms differ. APC provides up to $50K in AD&D / paralysis benefits and does not impose a per-tooth limit. Alternative Balance provides $5K in AD&D / paralysis benefits per accident, a $1M aggregate, and a $100 per-tooth limit. Both have a $500 deductible under the accident benefit.
The base price difference is only $6 per year. Both programs offer $2M / $4M headline liability limits and include Client Accident Protection and business property / income benefits. More meaningful differences include occurrence-based vs. claims-made Professional Liability, whether defense costs reduce the Professional Liability limits, Additional Insured fees, rented-premises restrictions, Client Accident benefit details, Identity Theft Protection, optional coverage, and financial strength ratings.
Comparison information reflects publicly available provider materials, policy information, and quote/application information reviewed in August 2026. Additional research and comparison information were reviewed and updated through September 2026. Coverage, pricing, eligibility, carrier information, and policy terms can change. APC publishes this comparison and is one of the insurance programs included in it. Alternative Balance has not reviewed, authorized, sponsored, or endorsed this comparison.
Where APC and Alternative Balance Are Similar
These two programs share several important features, which is one reason they can look quite similar at first glance.
Strong Liability Limits
Both offer $2 million / $4 million Professional Liability limits and $2 million / $4 million General Liability limits in the options reviewed.
Professional + General Liability
Both programs include Professional Liability and General Liability coverage for eligible services.
Business Property Protection
Both programs reviewed include $10,000 of Business Personal Property coverage and $10,000 of Business Income / Extra Expense protection.
Client / Participant Accident Benefits
Both include separate accident-related benefits for clients or participants, although the limits and structure differ.
Optional Cyber Coverage
Both offer optional Cyber coverage for an additional annual cost.
Optional Abuse / Misconduct Coverage
Both offer optional coverage related to sexual misconduct or abuse, with different pricing and policy terms.
The similarities are meaningful, but the way the policies respond to a claim and how certain benefits are structured is where the larger differences begin to appear.
Where APC and Alternative Balance Differ
The base prices and headline liability limits are similar, but the policies differ in Professional Liability structure, defense costs, Additional Insured fees, rented-premises coverage, Client Accident benefits, identity protection, financial strength, and how expanded services are priced.
1. Occurrence-Based vs. Claims-Made
APC Professional Liability is occurrence-based, so the key date is when the covered incident happened. Alternative Balance Professional Liability is claims-made, meaning coverage depends on the active policy period and when the claim is made. Both APC and Alternative Balance use occurrence-based General Liability coverage.
2. Defense Costs
APC defense costs are outside the liability limits, so legal defense expenses do not reduce the stated limit available for a covered settlement, judgment or claims. Alternative Balance defense costs are within the Professional Liability limits, so defense expenses will reduce the remaining limit.
3. Different Program Focus
APC is designed specifically for coaches and approved multimodality practices in the wellness, energy, holistic and fitness industries. Alternative Balance serves a broad mix of professions including tattooing, body piercing, permanent cosmetics, microneedling, and electrolysis, so the better fit may depend on the specific services you provide.
4. Additional Insured Costs
APC Professional and Premium include unlimited Additional Insureds at no extra fee. Alternative Balance charges $10 for each Additional Insured. This can matter for coaches who work with multiple facilities, organizations, landlords, or event hosts.
5. Damage to Premises Rented
Both provide a $300,000 limit, but the terms differ. APC does not use the same short-term rental restriction. Alternative Balance protection applies when the insured rents or has permission to use the premises for fewer than 7 days. This distinction may matter for coaches or practitioners who regularly rent offices, studios, treatment rooms, classrooms, or other spaces for longer periods.
6. Client Accident Protection
Both include accident-related medical protection, but the benefit structures differ.
APC: $25K medical per participant, per accident; up to $50K AD&D / paralysis; $500K aggregate per accident; $500 deductible; and no per-tooth limit.
Alternative Balance: $25K accidental medical per accident; $5K AD&D / paralysis per accident; $1M aggregate; $500 deductible per covered injury; and a $100 per-tooth limit.
7. Identity Theft Protection
APC Professional and Premium include up to $25,000 in Identity Theft Protection with no deductible. We did not identify a separate comparable Identity Theft benefit in the Alternative Balance base coverage reviewed.
8. Financial Strength Ratings
APC coverage is backed by Philadelphia Insurance Companies, rated A++ (Superior) by A.M. Best.
Alternative Balance links to an A.M. Best profile for LIO Specialty Insurance Company, showing an A- (Excellent) Financial Strength Rating. Both are strong ratings, with A++ representing the higher A.M. Best classification.
9. Base Annual Cost
The base-price difference is very small. APC Professional is $275 per year, while the Alternative Balance Professional Membership is $269 per year, a difference of only $6 per year. The larger differences are in how the policies and included benefits are structured.
10. Expanded Services Are Priced Differently
APC offers Premium Protection for $375 per year, covering a range of eligible modalities within one membership level.
Alternative Balance uses additional premiums for a number of services. Services such as cupping, nutritional consulting, sauna or float pod services, water therapies, and sports coaching / recreational fitness could add $139 each, with some other services carrying higher additional premiums.
The main takeaway: The base annual prices and liability limits are very close, but APC and Alternative Balance are not structured the same way. APC provides occurrence-based Professional Liability, defense costs outside the limits, unlimited Additional Insureds at no charge, Identity Theft Protection, Assault and Battery along with different Client Accident benefits. Alternative Balance has broader profession eligibility and may be a better fit for practitioners whose services fall outside APC’s coaching-focused scope, but some expanded services and Additional Insureds could significantly add to the annual cost.
APC vs. Alternative Balance Cost
For standard coaching services, the base annual prices are very close. The APC Professional plan is $275 per year, while the Alternative Balance Professional Membership reviewed was $269 per year. The comparison changes, however, when certain expanded or premium services are part of your practice.
APC Professional
Includes Professional and General Liability coverage, occurrence-based Professional Liability, defense costs outside the liability limits, and unlimited additional insureds at no extra fee.
Alternative Balance Professional Membership
Includes Professional and General Liability coverage. Professional Liability is claims-made, and additional insureds are $10 each.
Expanded Services Can Change the Price Comparison
APC offers a Premium Protection level at $375 per year that includes a range of eligible expanded services under one coverage level. Alternative Balance lists separate premiums for certain premium services on top of its Professional Membership.
| Example Service | APC Premium | Alternative Balance |
|---|---|---|
| Cupping | $375/year | $269 + $139 = $408/year |
| Nutritional Consulting | $375/year | $269 + $139 = $408/year |
| Sauna / Float Pod | $375/year | $269 + $139 = $408/year |
| Water Therapies | $375/year | $269 + $139 = $408/year |
| Acupuncture | $375/year | $269 + $249 = $518/year |
Examples above use services that appear in both programs' reviewed service information. Eligibility, service definitions, underwriting requirements, and policy terms may differ.
Optional Coverage Can Also Change the Final Price
Cyber Protection: $149/year
Sexual Misconduct & Abuse Protection: $169/year
CyberShield Plus: $169/year
Sexual Abuse Liability: $189/year
For standard coaching services, the base price difference is only $6 per year. For coaches whose practices include certain expanded services, comparing the total annual cost becomes more important. APC bundles a range of eligible expanded services into its $375 Premium Protection level, while Alternative Balance may add a separate premium for each applicable premium service.
Prices shown reflect the plans, premium-service pricing, and application information reviewed in August 2026 and may change. Actual pricing depends on services, eligibility, selections, underwriting, and policy terms.
Which May Be the Better Fit for You?
Both programs cover a wide range of coaching, wellness, energy, and holistic services. The better fit often comes down to policy structure, pricing, and whether your specific services fall within each program’s eligible scope.
APC May Be a Better Fit If You:
- Are a coach, holistic practitioner, energy practitioner, wellness professional, or have a practice that combines several of these services.
- Want a program designed around coaching and complementary practices.
- Prefer occurrence-based Professional Liability.
- Value defense costs outside the liability limits, so covered legal defense expenses do not reduce the stated liability limit available.
- Want unlimited additional insureds with no extra fee under the Professional or Premium plans.
- Provide one or more eligible expanded services and prefer APC’s $375 Premium Protection level rather than separate service-by-service premium charges.
Alternative Balance May Be a Better Fit If You:
- Provide a specific service that falls outside APC’s eligible scope but is expressly accepted by Alternative Balance.
- Need coverage for services such as permanent cosmetics, tattooing, body piercing, microneedling, electrolysis, or certain other specialized services, subject to Alternative Balance eligibility and pricing.
- Are comfortable with claims-made Professional Liability.
- Are comfortable paying additional premiums if required by certain services.
The difference is not simply coaching versus wellness. Both programs cover many coaching, wellness, energy, and holistic services. The more useful question is whether your specific work is eligible, how the policy protects you when a claim occurs, and what your total annual cost will be for the services you actually provide.
The Biggest Policy Difference: Occurrence vs. Claims-Made
Both APC and Alternative Balance offer substantial liability limits, but their Professional Liability coverage is structured differently. The timing of the incident and the claim can make a significant difference.
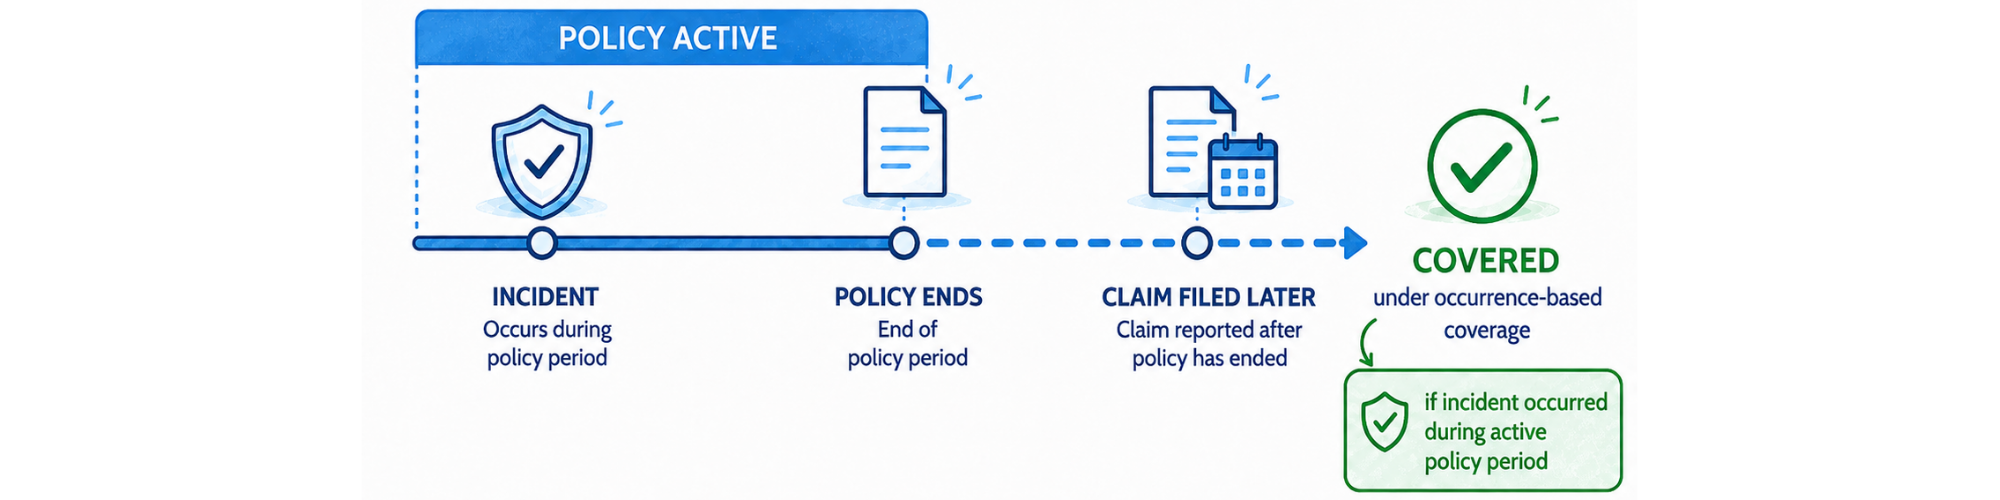
APC: Occurrence-Based
With occurrence-based Professional Liability, the key date is when the covered incident happened. If it occurred while the policy was active/in force, a claim reported later would still be covered under that policy period, subject to the policy terms.
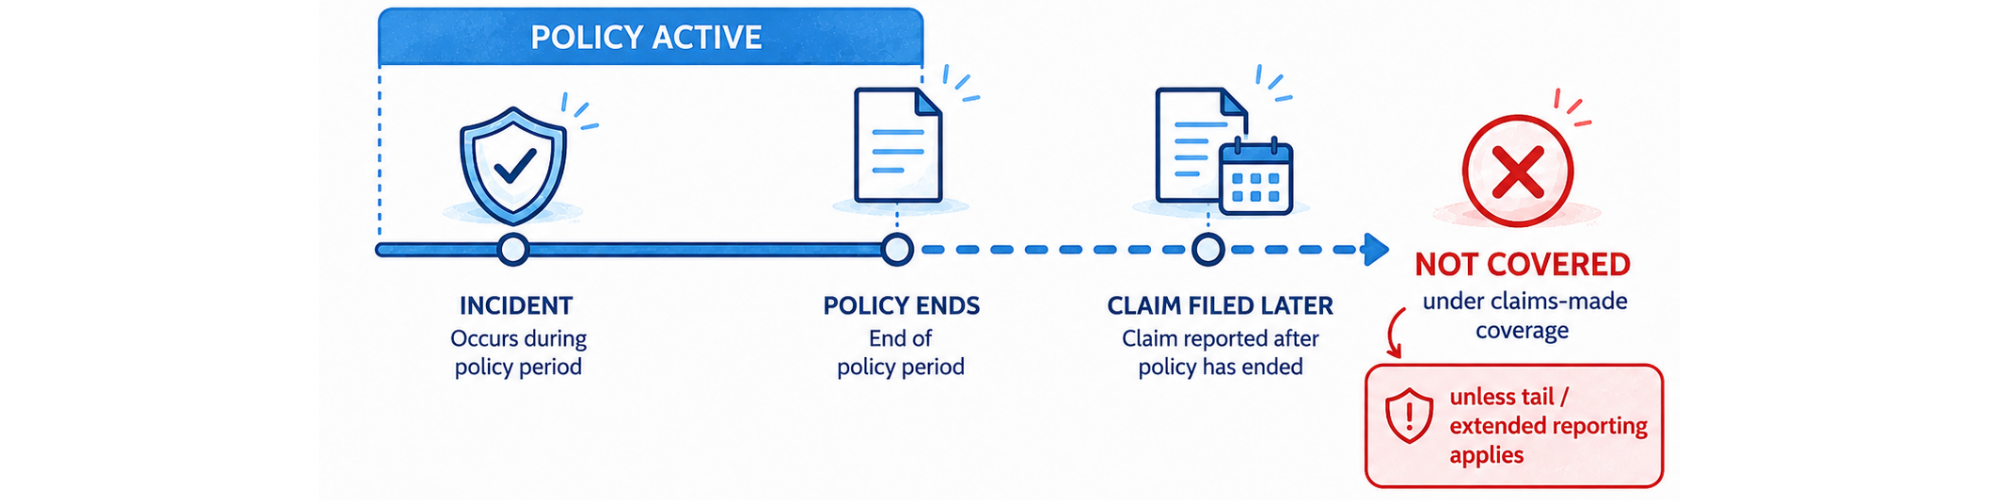
Alternative Balance: Claims-Made
With claims-made Professional Liability, coverage depends on both when the incident occurred and when the claim is made. The incident must occur during the policy term or during a predetermined retroactive date and be reported within the policy period or tail coverage timeframe.
Why this matters: Two policies can show similar limits and annual prices while providing different protection over time. Understanding whether Professional Liability is occurrence-based or claims-made is one of the most important parts of comparing the two programs.
Coverage is subject to the terms, conditions, limits, exclusions, eligibility requirements, and reporting provisions of the applicable policy.
How We Compared APC and Alternative Balance
Our goal is to make it easier to understand how APC and Alternative Balance compare using information a prospective customer could reasonably find or receive during the buying process.
Public Coverage Information
We reviewed publicly available coverage details, service lists, exclusions, FAQs, and other provider information.
Application & Pricing Review
Where useful, we also reviewed live application and pricing information to identify costs such as Additional Insured fees, premium-service charges, and optional coverage.
Unknowns Are Labeled
When a feature, limit, fee, or policy detail could not be clearly verified, we avoid assuming and identify it as not disclosed, not identified, or not verified.
Sources Reviewed
We used official APC and Alternative Balance information, along with application and pricing information available during our September 2026 review.
- APC Coverage & Pricing
- APC policy and program materials
- Alternative Balance Coverage & Pricing
- Alternative Balance Life Coaching & Consulting Insurance
- Alternative Balance Insurance FAQs
- Alternative Balance application and pricing information reviewed for Additional Insured fees, premium-service charges, and optional coverage
APC publishes this comparison and is one of the insurance programs included in it. Alternative Balance has not reviewed, authorized, sponsored, or endorsed this comparison.
Coverage, pricing, eligibility, carrier information, fees, and policy terms can change. Where a feature or policy detail could not be clearly confirmed, we identify it as not disclosed, not identified, or not verified rather than making assumptions. This comparison is intended to help readers evaluate the information reviewed and is not a substitute for the current policy documents. The policy itself controls in the event of any difference between a summary and the actual contract.
Research updated: September 2026
Insurance details reviewed by: APC’s Licensed Program Servicing Agent
APC vs. Alternative Balance FAQs
Here are answers to common questions about pricing, policy structure, covered services, and other differences between APC and Alternative Balance.
Still have questions? Visit the APC FAQ Hub or contact APC for help with your specific situation.
Is APC or Alternative Balance less expensive?
For the standard plans reviewed, the base prices are very close: APC Professional is $275 per year and Alternative Balance Professional Membership is $269 per year. The total cost can change depending on the services you provide, additional insureds, and optional coverage. Alternative Balance also charges additional premiums for certain premium services, while APC includes a range of expanded services under a set $375 Premium Protection level.
Does APC or Alternative Balance offer occurrence-based Professional Liability?
APC Professional Liability is occurrence-based. Coverage responds based on when the covered incident occurred. Alternative Balance Professional Liability is claims-made.
How do defense costs differ between APC and Alternative Balance?
With APC, defense costs are outside the liability limits, so covered legal defense expenses do not reduce the stated liability limit available for settlements, judgments or claims coverage.
Alternative Balance states that defense costs are within the Professional Liability limits, meaning covered defense expenses reduce the amount remaining for settlements, judgments or claims coverage.
Do APC and Alternative Balance cover the same kinds of services?
There is substantial overlap. Both programs cover many coaching, wellness, energy, and holistic services. However, their eligible-service lists are not identical. Alternative Balance also accepts some specialized services outside APC’s scope, while APC provides coverage for a wide range of coaching and complementary practices. Always confirm that your specific services are eligible before purchasing coverage.
Which may be better if I offer several different services?
That depends on the services you provide. APC may be a strong fit for coaches and practitioners who combine coaching, wellness, energy, and holistic services. Its Premium Protection level includes a range of expanded services for one annual price. Alternative Balance may be a better fit when a specific service falls outside APC’s eligible scope but is expressly accepted by Alternative Balance.
How do additional insureds compare?
APC Professional and Premium plans allow unlimited additional insureds with no extra fee.
In the Alternative Balance application reviewed, additional insureds were $10 each. This may matter if you regularly work with facilities, landlords, event hosts, organizations, or other businesses that require additional insured status.
How does rented-premises coverage compare?
Both programs list $300,000 in Damage to Premises Rented coverage.
APC does not use the same fewer-than-7-days restriction described in the Alternative Balance coverage reviewed.
Alternative Balance coverage applies when the insured rents or has permission to use the premises for fewer than 7 days.
Which company has the stronger A.M. Best rating?
The carrier behind APC coverage is rated A++ (Superior) by A.M. Best. Alternative Balance lists an A- (Excellent) rating for its liability carrier. Both are strong financial strength ratings, but A++ is the higher rating.
Is APC or Alternative Balance the better liability insurance option?
There is no single policy that is best for every professional. APC may be a strong fit for coaches and practitioners who want occurrence-based Professional Liability, defense costs outside the liability limits, unlimited additional insureds, and coverage designed around coaching and related practices.
Alternative Balance may be a better fit when your work includes a specific service that APC does not insure but Alternative Balance accepts. Compare eligibility, policy structure, limits, included benefits, and total cost before deciding.
Who created this APC vs. Alternative Balance comparison?
The Association of Professional Coaches (APC) created this comparison using APC program and policy information, Alternative Balance published materials, and application or pricing information reviewed in 2026. APC is one of the insurance programs included in the comparison. Alternative Balance has not reviewed, authorized, sponsored, or endorsed this comparison.
Coverage information is provided for general educational purposes. Actual coverage is subject to eligibility and the terms, conditions, limits, exclusions, and endorsements of the policy. Comparison information was last reviewed in September 2026.
Explore More Coach Insurance Comparisons
Want to compare APC with other coach liability insurance providers? Explore additional side-by-side comparisons or return to the complete comparison guide.
APC vs. Insurance Canopy
Compare liability limits, occurrence-based coverage, included protections, optional add-ons, and annual pricing.
Compare APC vs. Insurance Canopy →APC vs. Hiscox
Compare Professional Liability limits, claims-made vs. occurrence-based coverage, business insurance options, included protections, and pricing.
Compare APC vs. Hiscox →APC vs. CPH Insurance
Compare occurrence-based Professional Liability, liability limits, included and optional protections, business coverage, and annual pricing.
Compare APC vs. CPH Insurance →APC vs. CM&F
Compare liability limits, occurrence-based Professional Liability, included protections, Medical Expense benefits, and annual cost.
Compare APC vs. CM&F →APC vs. ERGO NEXT
Compare liability limits, claims-made vs. occurrence-based coverage, defense costs, Cyber protection, included benefits, and pricing.
Compare APC vs. ERGO NEXT →Compare Coach Liability Insurance
Compare APC and multiple coach liability insurance providers in one side-by-side guide.
View the Complete Comparison →Choose Coverage That Fits the Way You Work
APC combines Professional Liability and General Liability coverage with occurrence-based protection, defense costs outside the liability limits, individual member limits, and straightforward annual pricing for eligible practices.
Review the coverage details, confirm that your services are eligible, and choose the protection level that fits your practice.
Not sure whether your services qualify? Check Your Coverage →
More Resources for Choosing Coach Liability Insurance
Want to learn more before choosing coverage? These resources can help you understand coach liability insurance, compare protection, and make a more informed decision for your practice.
Complete Guide to Liability Insurance for Coaches
Learn how coach liability insurance works, including coverage types, policy limits, claims, costs, Certificates of Insurance, and common questions.
Read the Complete Guide →APC Learning Center
Explore practical articles and resources on coach liability insurance, professional practice, risk management, and protecting your coaching business.
Visit the Learning Center →Professional Liability vs. General Liability
Understand the difference between claims related to your professional coaching services and claims involving third-party injury or property damage.
Compare the Two Coverages →NEED HELP CHOOSING?
Not sure which coverage fits the way you work? Explore your options or let APC help confirm your coverage fit.